


SIP investing
Invest a fixed amount every month and let it add up. Start, pause or step it up any time.
Your mutual fund investment partner, simplified
Mutual funds, SIPs and tax saving, set up with Solid Wealth and tracked in your own app.
What we do
Invest a fixed amount every month and let it add up. Start, pause or step it up any time.
Put a bonus, maturity or savings to work in one go, in funds that match how long you can stay invested.
Claim up to Rs 1.5 lakh under Section 80C with a three year lock-in, the shortest among 80C options.
A home, a child’s education, retirement. Each goal gets its own plan and its own progress bar.
Bring investments you made elsewhere. We show them in one view and go through them with you.
Answer a short questionnaire in the app to see your risk profile before you choose a fund.
How it works
Tell us what you are saving for and by when. A short call is enough.
PAN, personal details, bank account and nominee, all on your phone. No paperwork.
Every SIP, goal and statement in one place, whenever you want to look.
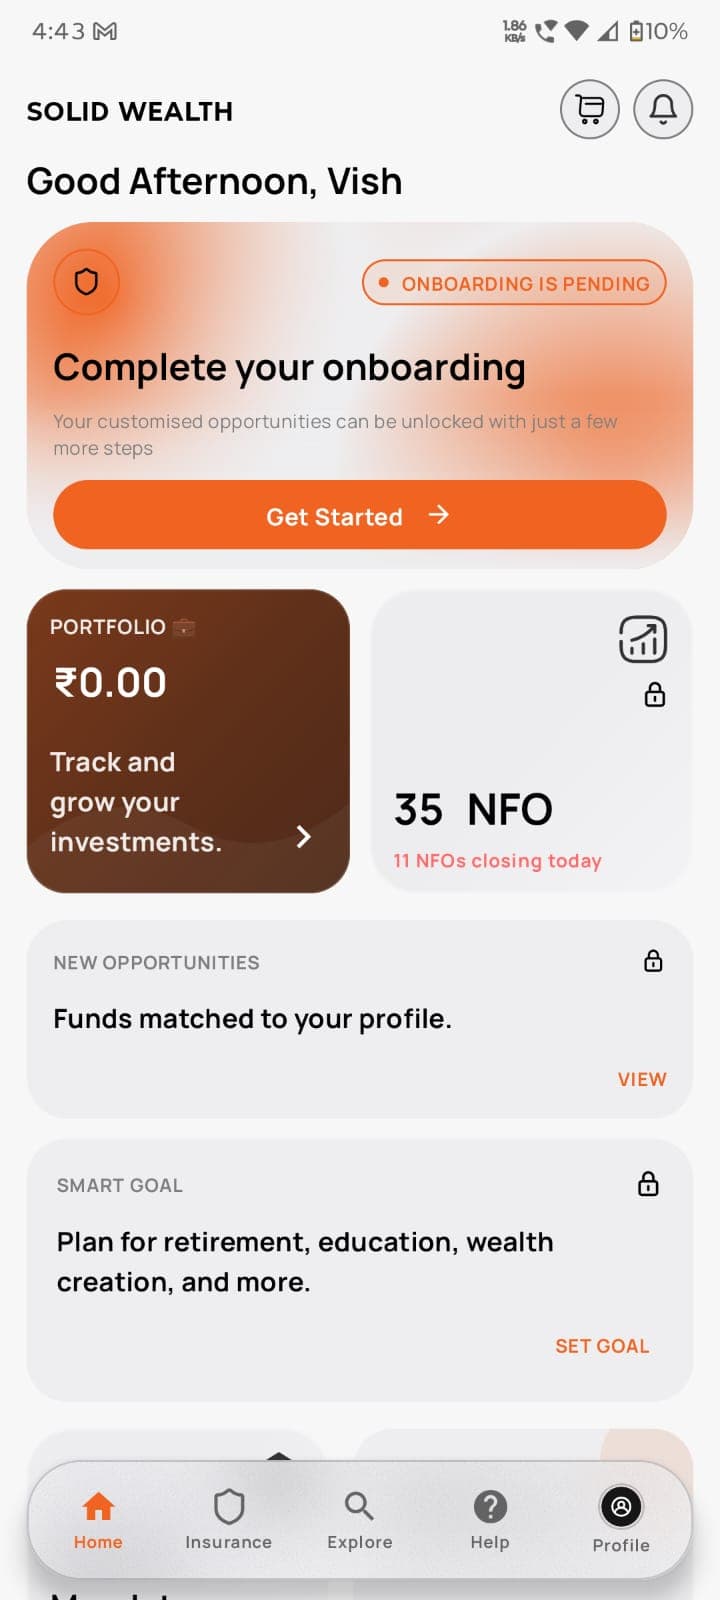
The Solid Wealth app
See what you own, what it is worth and how each fund is doing. Check your risk profile, and start a SIP in a few taps.
Calculators
What a monthly SIP grows to.
| Year | Invested | Value |
|---|---|---|
| 1 | ₹60,000 | ₹64,047 |
| 2 | ₹1,20,000 | ₹1,36,216 |
| 3 | ₹1,80,000 | ₹2,17,538 |
| 4 | ₹2,40,000 | ₹3,09,174 |
| 5 | ₹3,00,000 | ₹4,12,432 |
| 6 | ₹3,60,000 | ₹5,28,785 |
| 7 | ₹4,20,000 | ₹6,59,895 |
| 8 | ₹4,80,000 | ₹8,07,633 |
| 9 | ₹5,40,000 | ₹9,74,108 |
| 10 | ₹6,00,000 | ₹11,61,695 |
A 2-page report with the method and schedule.
Each instalment is invested at the start of the month and compounds monthly at the annual return divided by 12. Maturity = P × [((1 + i)n − 1) ÷ i] × (1 + i), where P is the monthly SIP, i the monthly rate and n the number of months. ₹5,000 a month for 10 years at 12% comes to ₹11,61,695.
FV = P × [((1 + i)^n − 1) ÷ i] × (1 + i)A SIP that rises every year.
| Year | Invested | Value |
|---|---|---|
| 1 | ₹60,000 | ₹64,047 |
| 2 | ₹1,26,000 | ₹1,42,621 |
| 3 | ₹1,98,600 | ₹2,38,205 |
| 4 | ₹2,78,460 | ₹3,53,661 |
| 5 | ₹3,66,306 | ₹4,92,285 |
| 6 | ₹4,62,937 | ₹6,57,867 |
| 7 | ₹5,69,230 | ₹8,54,764 |
| 8 | ₹6,86,153 | ₹10,87,978 |
| 9 | ₹8,14,769 | ₹13,63,250 |
| 10 | ₹9,56,245 | ₹16,87,163 |
A 2-page report with the method and schedule.
The SIP starts at the amount you enter and rises by the step-up percentage every 12 months. Each instalment compounds monthly from the day it goes in, so the result is the sum of every instalment's growth to the end date.
B(m) = (B(m − 1) + SIP(m)) × (1 + i)What a one-time investment grows to.
| Year | Invested | Value |
|---|---|---|
| 1 | ₹1,00,000 | ₹1,12,000 |
| 2 | ₹1,00,000 | ₹1,25,440 |
| 3 | ₹1,00,000 | ₹1,40,493 |
| 4 | ₹1,00,000 | ₹1,57,352 |
| 5 | ₹1,00,000 | ₹1,76,234 |
| 6 | ₹1,00,000 | ₹1,97,382 |
| 7 | ₹1,00,000 | ₹2,21,068 |
| 8 | ₹1,00,000 | ₹2,47,596 |
| 9 | ₹1,00,000 | ₹2,77,308 |
| 10 | ₹1,00,000 | ₹3,10,585 |
A 2-page report with the method and schedule.
A single amount compounds once a year at the return you enter. Future value = P × (1 + r)t, where r is the annual return and t the number of years.
FV = P × (1 + r)^tA monthly payout from a corpus.
| Year | Withdrawn | Balance |
|---|---|---|
| 1 | ₹3,60,000 | ₹50,41,500 |
| 2 | ₹7,20,000 | ₹50,86,444 |
| 3 | ₹10,80,000 | ₹51,35,119 |
| 4 | ₹14,40,000 | ₹51,87,833 |
| 5 | ₹18,00,000 | ₹52,44,923 |
| 6 | ₹21,60,000 | ₹53,06,751 |
| 7 | ₹25,20,000 | ₹53,73,711 |
| 8 | ₹28,80,000 | ₹54,46,229 |
| 9 | ₹32,40,000 | ₹55,24,765 |
| 10 | ₹36,00,000 | ₹56,09,820 |
| 11 | ₹39,60,000 | ₹57,01,935 |
| 12 | ₹43,20,000 | ₹58,01,695 |
| 13 | ₹46,80,000 | ₹59,09,735 |
| 14 | ₹50,40,000 | ₹60,26,742 |
| 15 | ₹54,00,000 | ₹61,53,461 |
A 2-page report with the method and schedule.
The corpus earns the annual return divided by 12 each month, and the withdrawal comes out at the end of the month. If the withdrawal is more than the corpus earns, the corpus runs down, and the result shows the month it runs out.
B(m) = B(m − 1) × (1 + i) − WThe monthly SIP a goal needs.
| Year | Invested | Value |
|---|---|---|
| 1 | ₹1,87,325 | ₹1,99,959 |
| 2 | ₹3,74,650 | ₹4,25,278 |
| 3 | ₹5,61,975 | ₹6,79,173 |
| 4 | ₹7,49,300 | ₹9,65,268 |
| 5 | ₹9,36,625 | ₹12,87,647 |
| 6 | ₹11,23,950 | ₹16,50,911 |
| 7 | ₹13,11,275 | ₹20,60,247 |
| 8 | ₹14,98,600 | ₹25,21,497 |
| 9 | ₹16,85,925 | ₹30,41,245 |
| 10 | ₹18,73,250 | ₹36,26,910 |
| 11 | ₹20,60,575 | ₹42,86,852 |
| 12 | ₹22,47,900 | ₹50,30,491 |
A 2-page report with the method and schedule.
The goal's cost today is first grown by inflation to the year you need it. The monthly SIP is then the instalment that reaches that amount at the return you enter, using the same monthly compounding as the SIP calculator.
SIP = Cost × (1 + f)^t ÷ ([((1 + i)^n − 1) ÷ i] × (1 + i))What waiting to start costs.
| Year | Start today | Start later |
|---|---|---|
| 1 | ₹1,28,093 | ₹0 |
| 2 | ₹2,72,432 | ₹1,28,093 |
| 3 | ₹4,35,076 | ₹2,72,432 |
| 4 | ₹6,18,348 | ₹4,35,076 |
| 5 | ₹8,24,864 | ₹6,18,348 |
| 6 | ₹10,57,570 | ₹8,24,864 |
| 7 | ₹13,19,790 | ₹10,57,570 |
| 8 | ₹16,15,266 | ₹13,19,790 |
| 9 | ₹19,48,215 | ₹16,15,266 |
| 10 | ₹23,23,391 | ₹19,48,215 |
| 11 | ₹27,46,148 | ₹23,23,391 |
| 12 | ₹32,22,522 | ₹27,46,148 |
| 13 | ₹37,59,311 | ₹32,22,522 |
| 14 | ₹43,64,180 | ₹37,59,311 |
| 15 | ₹50,45,760 | ₹43,64,180 |
| 16 | ₹58,13,782 | ₹50,45,760 |
| 17 | ₹66,79,208 | ₹58,13,782 |
| 18 | ₹76,54,392 | ₹66,79,208 |
| 19 | ₹87,53,254 | ₹76,54,392 |
| 20 | ₹99,91,479 | ₹87,53,254 |
A 2-page report with the method and schedule.
Both SIPs end on the same date. One starts today, the other after the delay, so it gets fewer instalments and less time to compound. The cost of waiting is the difference between the two final values.
Cost = FV(P, i, n) − FV(P, i, n − d)For illustration only. Results depend on the return you enter and are not a promise of future returns.
About us
Solid Wealth
Solid Wealth helps individuals and businesses grow, protect and preserve their wealth through mutual fund investments. You get one team to call, a clear plan for each goal, and an app that shows every rupee.
Questions
Your money goes straight from your bank account to the fund house. We never hold it. Units are held in your name and every transaction is confirmed to you by CAMS or KFintech.
Many funds accept a SIP from Rs 500 a month. The minimum depends on the scheme, and we will tell you before you invest.
Yes. You can pause, stop, or increase a SIP at any time. There is no penalty from us, though some schemes carry an exit load on early redemption.
Neither is better every time. A SIP spreads your entry across market levels and suits money you earn monthly. A lumpsum puts the full amount to work at once, which helps when markets rise steadily afterwards. The calculators above show both.
Your PAN, personal details, bank account and a nominee. It is done online in the app in a few minutes, and you only do it once.
Yes. Add your outside mutual funds to the app and they show next to the ones made with us.
Contact
Tell us your financial goals and we will help you build a plan for long-term growth.